Three months after setting a $7.5 billion target for AI sales to the big cloud companies, Cisco raised it by $1.5 billion. The networking company now expects $9 billion in AI infrastructure revenue from hyperscalers in its 2027 fiscal year, up from the $7.5 billion it projected in August and more than double the roughly $4 billion it delivered in fiscal 2026.
The bigger shift is in who else is buying. Product orders rose 21% in the quarter that ended Oct. 24, and orders excluding hyperscalers rose 14%, Chief Executive Chuck Robbins said in prepared remarks for Thursday’s earnings call. Enterprise orders were up 15%, on top of 4% growth a year earlier. The numbers show AI networking demand reaching beyond the cloud giants.
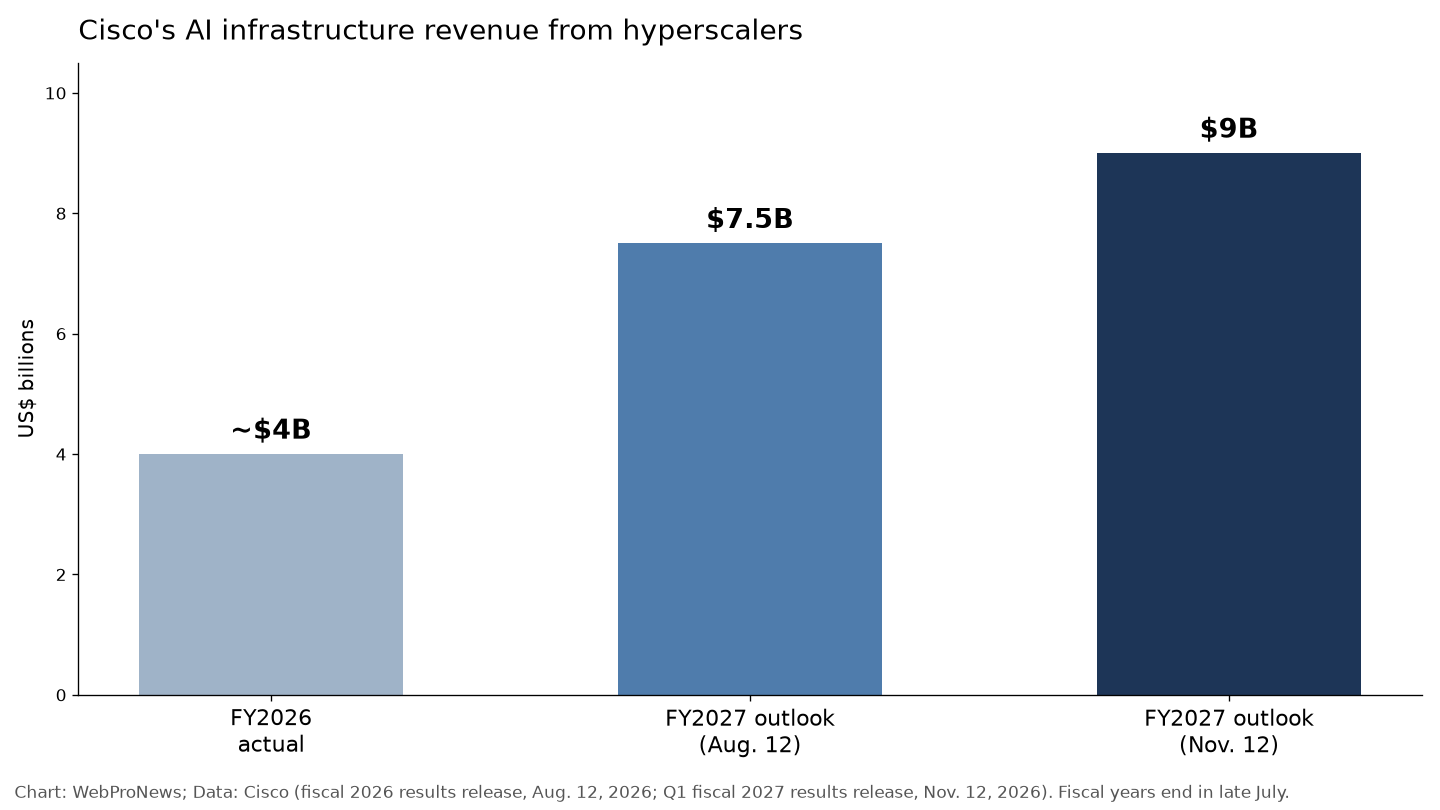
Cisco’s shares fell in extended trading after the August report, CNBC said. The target is for revenue, not orders. Cisco took $9.3 billion in hyperscaler AI orders during fiscal 2026 but delivered about $4 billion of revenue from that business that year, so the $9 billion for fiscal 2027 measures a different thing. Cisco won three new AI design wins in the quarter, two for systems built on its Silicon One P200 chip and one for 1.6-terabit optics, an area of AI networking that also drew Marvell’s $115 billion all-stock deal for Lumentum earlier this month.
Revenue and adjusted earnings grew at their fastest rates in more than 15 years, Cisco said in its results release. Revenue rose 24% to $18.5 billion, and adjusted earnings rose 40% to $1.40 a share. Analysts polled by LSEG had expected $18.1 billion and $1.33, CNBC reported. Networking product revenue jumped 43%, while security grew 7% and services just 1%.
Cisco now sees fiscal 2027 revenue of $74.8 billion to $75.8 billion, up from the $72.2 billion to $73.4 billion it guided in August. Its adjusted earnings outlook moved to $5.47 to $5.53 a share, from $5.05 to $5.11.
“We are in the very early stages of a multi-year networking supercycle,” Robbins said in the release. On the call, he pointed to demand beyond the cloud giants. AI infrastructure orders from neocloud, sovereign and enterprise customers accelerated, he said, and orders for Nexus data center switches tagged for AI deployments rose 47%. Campus networking orders grew 14%. Robbins described the AI-driven networking cycle as still early, “with enterprise adoption just beginning.”
The cost of that growth shows up in margins. Adjusted gross margin fell 250 basis points from a year earlier to 65.6%, and adjusted product gross margin dropped 350 basis points to 63.7%. Chief Financial Officer Mark Patterson attributed the product margin decline mainly to a heavier mix of hardware and “elevated memory costs,” partly offset by productivity improvements and price increases. A global memory-chip shortage has been raising component costs for hardware makers, SiliconANGLE noted.
Patterson said hyperscale AI should make up 12% of Cisco’s total revenue this fiscal year, double its 6% share in fiscal 2026. Headcount has fallen by a low single-digit percentage, and Cisco expects revenue per employee to rise about 19%. The company returned $3.7 billion to shareholders in the quarter through dividends and buybacks.
The next read on enterprise demand comes Feb. 10, when Cisco reports a quarter it has guided to $18 billion to $18.2 billion in revenue, above the $17.88 billion analysts expected in LSEG data cited by CNBC. Security may get attention sooner. Robbins said Splunk is exploring, with a hyperscaler Cisco did not name, how AI agents can help security teams investigate threats, and the company has more to share later this month.